
The Walmart 401k match is dollar for dollar, up to 6% of eligible pay, once you’re match-eligible. Every matched dollar is 100% vested from the day it lands, according to the Walmart 401(k) Plan summary in Walmart’s 2026 Associate Benefits Book.
The catch sits in front of the match. You can contribute from your first weeks, but Walmart adds nothing until you’ve been credited with 1,000 hours of service. The plan summary says contributions made before that point are never matched. Miss that detail and you’ll spend a year assuming free money is piling up when it isn’t.
When does the Walmart 401(k) match start?
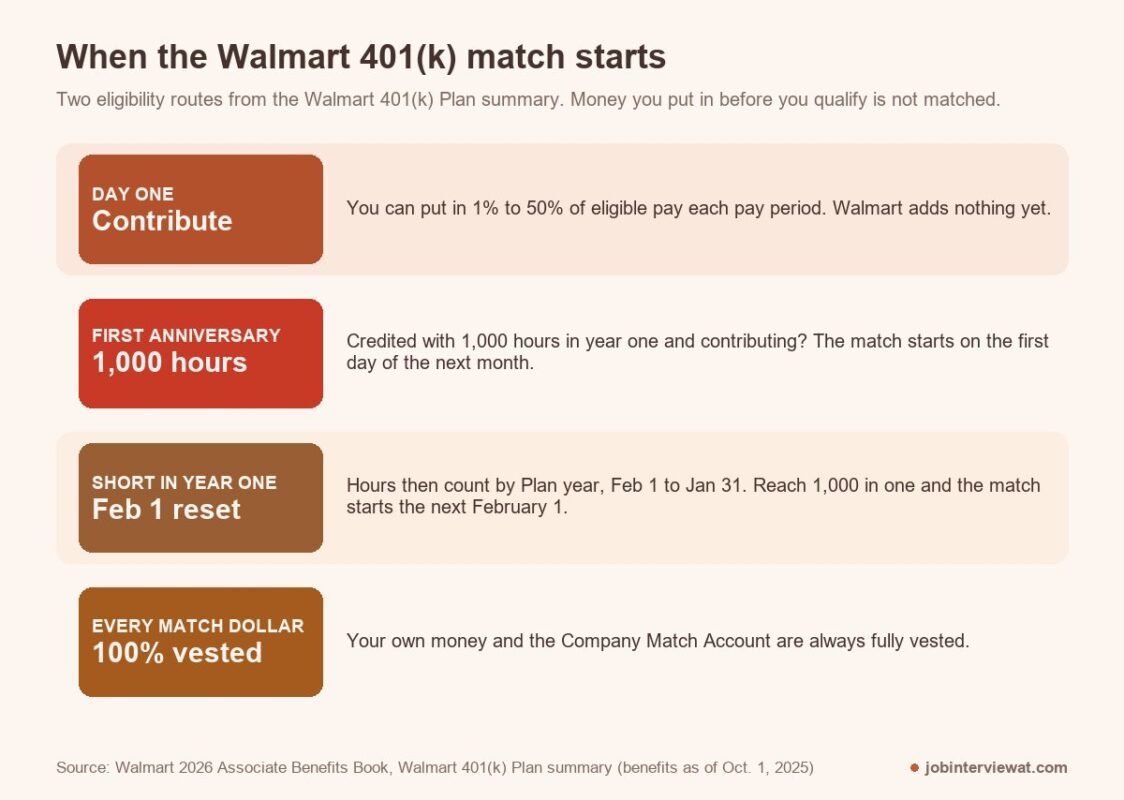
The Walmart 401(k) match starts on the first day of the calendar month after your first work anniversary. Two conditions apply: at least 1,000 hours of service credited in that first year, and contributions of your own going in. That’s the timing in Walmart’s 2026 Associate Benefits Book, which carries the plan’s summary as of October 1, 2025.
The summary’s own example makes it concrete. An associate hired December 15, 2024, who reached 1,095 hours by December 15, 2025, started receiving the match on January 1, 2026. Only contributions from that date on were matched.
What if you come up short in year one? Your hours then count by Plan year, which runs February 1 to January 31. The match begins the February 1 after the Plan year in which you reach 1,000 hours.
Is a part-time schedule enough? By plain division, 1,000 hours across 52 weeks averages a little over 19 hours a week. A steady part-time schedule can clear that. A seasonal stint with long gaps often won’t.
One more condition applies to a small group. The 2026 plan summary says highly compensated employees must also be at least 21.
Hours that count toward the 1,000
For hourly associates, the 2026 plan summary counts hours worked, overtime included, plus hours paid as leave or personal time off. Salaried associates and truck drivers get a flat 190 hours for each month in which they work at least one hour.
Leaving early doesn’t always wipe the slate. An associate who leaves in the first year with more than 500 hours keeps those hours and the first-anniversary date for match purposes, the summary says, if they’re rehired.
How much does Walmart put in, and on which pay?
Walmart’s match equals 100% of what you contribute, capped at 6% of eligible annual pay for the Plan year. It’s deposited each pay period until the cap’s reached. Walmart’s corporate benefits page, checked October 2026, puts it the same way: Walmart “will match each dollar they contribute, up to 6% of their eligible pay.”
Here’s an illustration, not a Walmart figure. Say your eligible pay for the Plan year is $30,000. Put in 6% and you’ve contributed $1,800, and the match adds another $1,800. Put in 3% and the match is $900. Put in 10% and the match still stops at $1,800, because the cap is tied to 6% of pay.
Eligible pay is broader than base wages. The 2026 plan summary counts regular wages, overtime, paid time off, holiday bonuses and other bonuses. It leaves out signing bonuses, severance, expense reimbursements and the 15% match Walmart pays into the Associate Stock Purchase Plan. That stock plan and the associate discount card sit beside the 401(k); the Walmart employee discount breakdown covers how the card works.
You can choose pretax, Roth or a mix, at 1% to 50% of each paycheck. The IRS cap on your own contributions is $24,500 for 2026, per the plan summary. Catch-up room adds $8,000 at age 50 or older, or $11,250 for associates turning 60, 61, 62 or 63 that year.
Higher earners in the Walmart 401k face a timing trap. The 6% match cap runs on the Plan year, February through January, while the $24,500 limit runs on the calendar year. The summary warns that maxing out early in a calendar year can leave some money unmatched. Near the limit? Steady contributions all year are the safer pattern.
Enrolling, changing your rate and borrowing
Walmart’s 2026 plan summary doesn’t describe automatic enrollment in the Walmart 401k. Shortly after you’re hired, an enrollment packet goes to your home address. You enroll yourself through One.Walmart.com, through benefits.ml.com (the Plan’s website, run by Merrill), or by calling the Customer Service Center at 888-968-4015.
Didn’t pick investments? Your money goes into the Plan’s default option, the myRetirement Funds. Changes take effect within about two pay periods, the summary says, and you can raise, lower, stop or restart contributions at any time.
The summary also puts the burden on the associate to confirm the deduction is right. A mistake reported more than three months after the election isn’t timely, and the amount being withheld is then treated as what you chose. Your stub is where that deduction shows up, and the Walmart pay stub guide covers where to find it, including the separate portal former associates use.
I spent nearly three years on Walmart’s recruiting side, not at its benefits desk. For anything about your own balance or a pending request, the Customer Service Center number above is the place to ask.
Loans and hardship withdrawals while you still work there
Can you get at the money before you leave? The plan summary lists a few ways. Loans start at $1,000, top out at the lesser of 50% of your vested balance or $50,000, and repay over one to five years, with a longer term for a home purchase.
There’s also a hardship withdrawal for needs such as uninsured medical bills or preventing eviction. The summary adds a limited emergency withdrawal of up to $1,000 once per calendar year, up to $5,000 after a birth or adoption, and full access to the vested balance after age 59½. Each one has tax consequences, and a loan that goes into default can be treated as a taxable distribution. Ask the plan or a tax professional before you take one, since the tax hit lands on you.
Your Walmart 401k after your last shift
You keep all of it. Under the 2026 plan summary, your contributions and Walmart’s match are 100% vested, so leaving after six months or six years takes nothing back. The one exception is an older Company Funded Profit Sharing Account holding Walmart contributions from Plan years that ended by January 31, 2011. That account vests on a schedule from 20% at two years of service to 100% at six.
The temptation shows up fast. One associate, around four years in by their own count, posted this in June 2026:
“I have worked for Walmart for a good few years and have been contributing to it for most of them and i just want my money. Ik if i take it out ill be taxed at the end of year for it but idrc.” (excerpt)
– r/WalmartEmployees, June 2026 (3 upvotes)
Income tax is only part of the bill. The IRS page on early distributions, last reviewed December 2025, says withdrawals before age 59½ generally owe an additional 10% tax unless an exception applies. One listed exception covers leaving your employer during or after the year you turn 55.
Once you’re gone, the plan summary describes three paths:
- Leave it in the plan. Balances over $1,000 can stay until age 72½, and you can still change investments, but an annual maintenance fee applies.
- Roll it over. A direct rollover to an IRA or a new employer’s plan postpones the tax, the summary says. Requests go through benefits.ml.com or the Customer Service Center.
- Cash it out. Taxes are withheld from the check, a processing fee comes off the balance, and the IRS early-withdrawal tax above can apply.
This is general plan information, not tax or investment advice. Before you pick a path, talk through your own numbers with the plan’s Customer Service Center or a tax professional.
Two timing details catch people. You can elect a payout 30 calendar days after your termination is entered into payroll. If the vested balance is $1,000 or less, the plan pays it out in cash automatically after the third calendar month following that entry, unless you’ve arranged a rollover with the Customer Service Center.
One associate described the paperwork arriving on its own in July 2026:
“Within 30 days of your termination date you will receive a letter from Merrill Lynch about your 401(k) that will detail your options and how to proceed.”
– r/WalmartEmployees, July 2026 (5 upvotes)
Nothing in the mail after two months? The plan summary says to call 888-968-4015 if no payout information has arrived within 60 days of your termination date. Update your mailing address before your last day, since the notice goes to the address on file.
Coming back changes things too. If you’re rehired before the payout is finished, it’s canceled. If you’d already qualified for the match when you left, you’re match-eligible again on your rehire date, the summary says. Planning your exit? The two weeks notice guide covers the resignation itself, and our Walmart starting pay breakdown covers what the job pays.
Walmart 401k FAQ
Does Walmart match 401(k) contributions?
Yes. Walmart matches 100% of what you contribute, up to 6% of eligible pay, once you’re match-eligible under the Walmart 401(k) Plan, according to its 2026 Associate Benefits Book. Contributions made before eligibility aren’t matched.
When are you eligible for Walmart’s 401(k)?
You can contribute to Walmart’s 401(k) once you’re set up in payroll after hire. The match begins the first of the month after the first anniversary for anyone credited with 1,000 hours that year; otherwise, it starts the February 1 after a Plan year with 1,000 hours.
How long does it take to be vested in Walmart’s 401(k)?
There’s no wait. Walmart’s 2026 plan summary says you’re always 100% vested in your own contributions and in Walmart’s matching contributions. Only an older profit-sharing account, funded with Walmart contributions for Plan years through January 2011, follows a two-to-six-year vesting schedule.
What happens to my Walmart 401(k) if I quit?
A vested Walmart 401(k) stays yours after you quit. A balance over $1,000 can stay in the plan, roll into an IRA or another employer’s plan, or be cashed out, which can trigger income tax and the IRS 10% early-withdrawal tax before age 59½. Balances of $1,000 or less are paid out automatically.
How do I access my Walmart 401(k)?
Walmart’s plan summary points associates to benefits.ml.com, the Plan’s Merrill-run website, or to the Customer Service Center at 888-968-4015. Current associates can also change contributions through One.Walmart.com, and former associates use benefits.ml.com or the phone line to request a payout.